Should You List Your West Michigan Home Before the Holidays—or Wait Until 2027?
Listing before the holidays can mean fewer new competitors, but buyers also have more total choices and mortgage rates remain above 7%. Here is how West Michigan homeowners can decide whether to launch now, prepare for January or build a different timeline.

Your Home Listing Expired. Now What? A West Michigan Seller's Guide
Your West Michigan listing expired. Use real buyer feedback, current competition, and a practical RESET checklist to decide what to change before you relist.
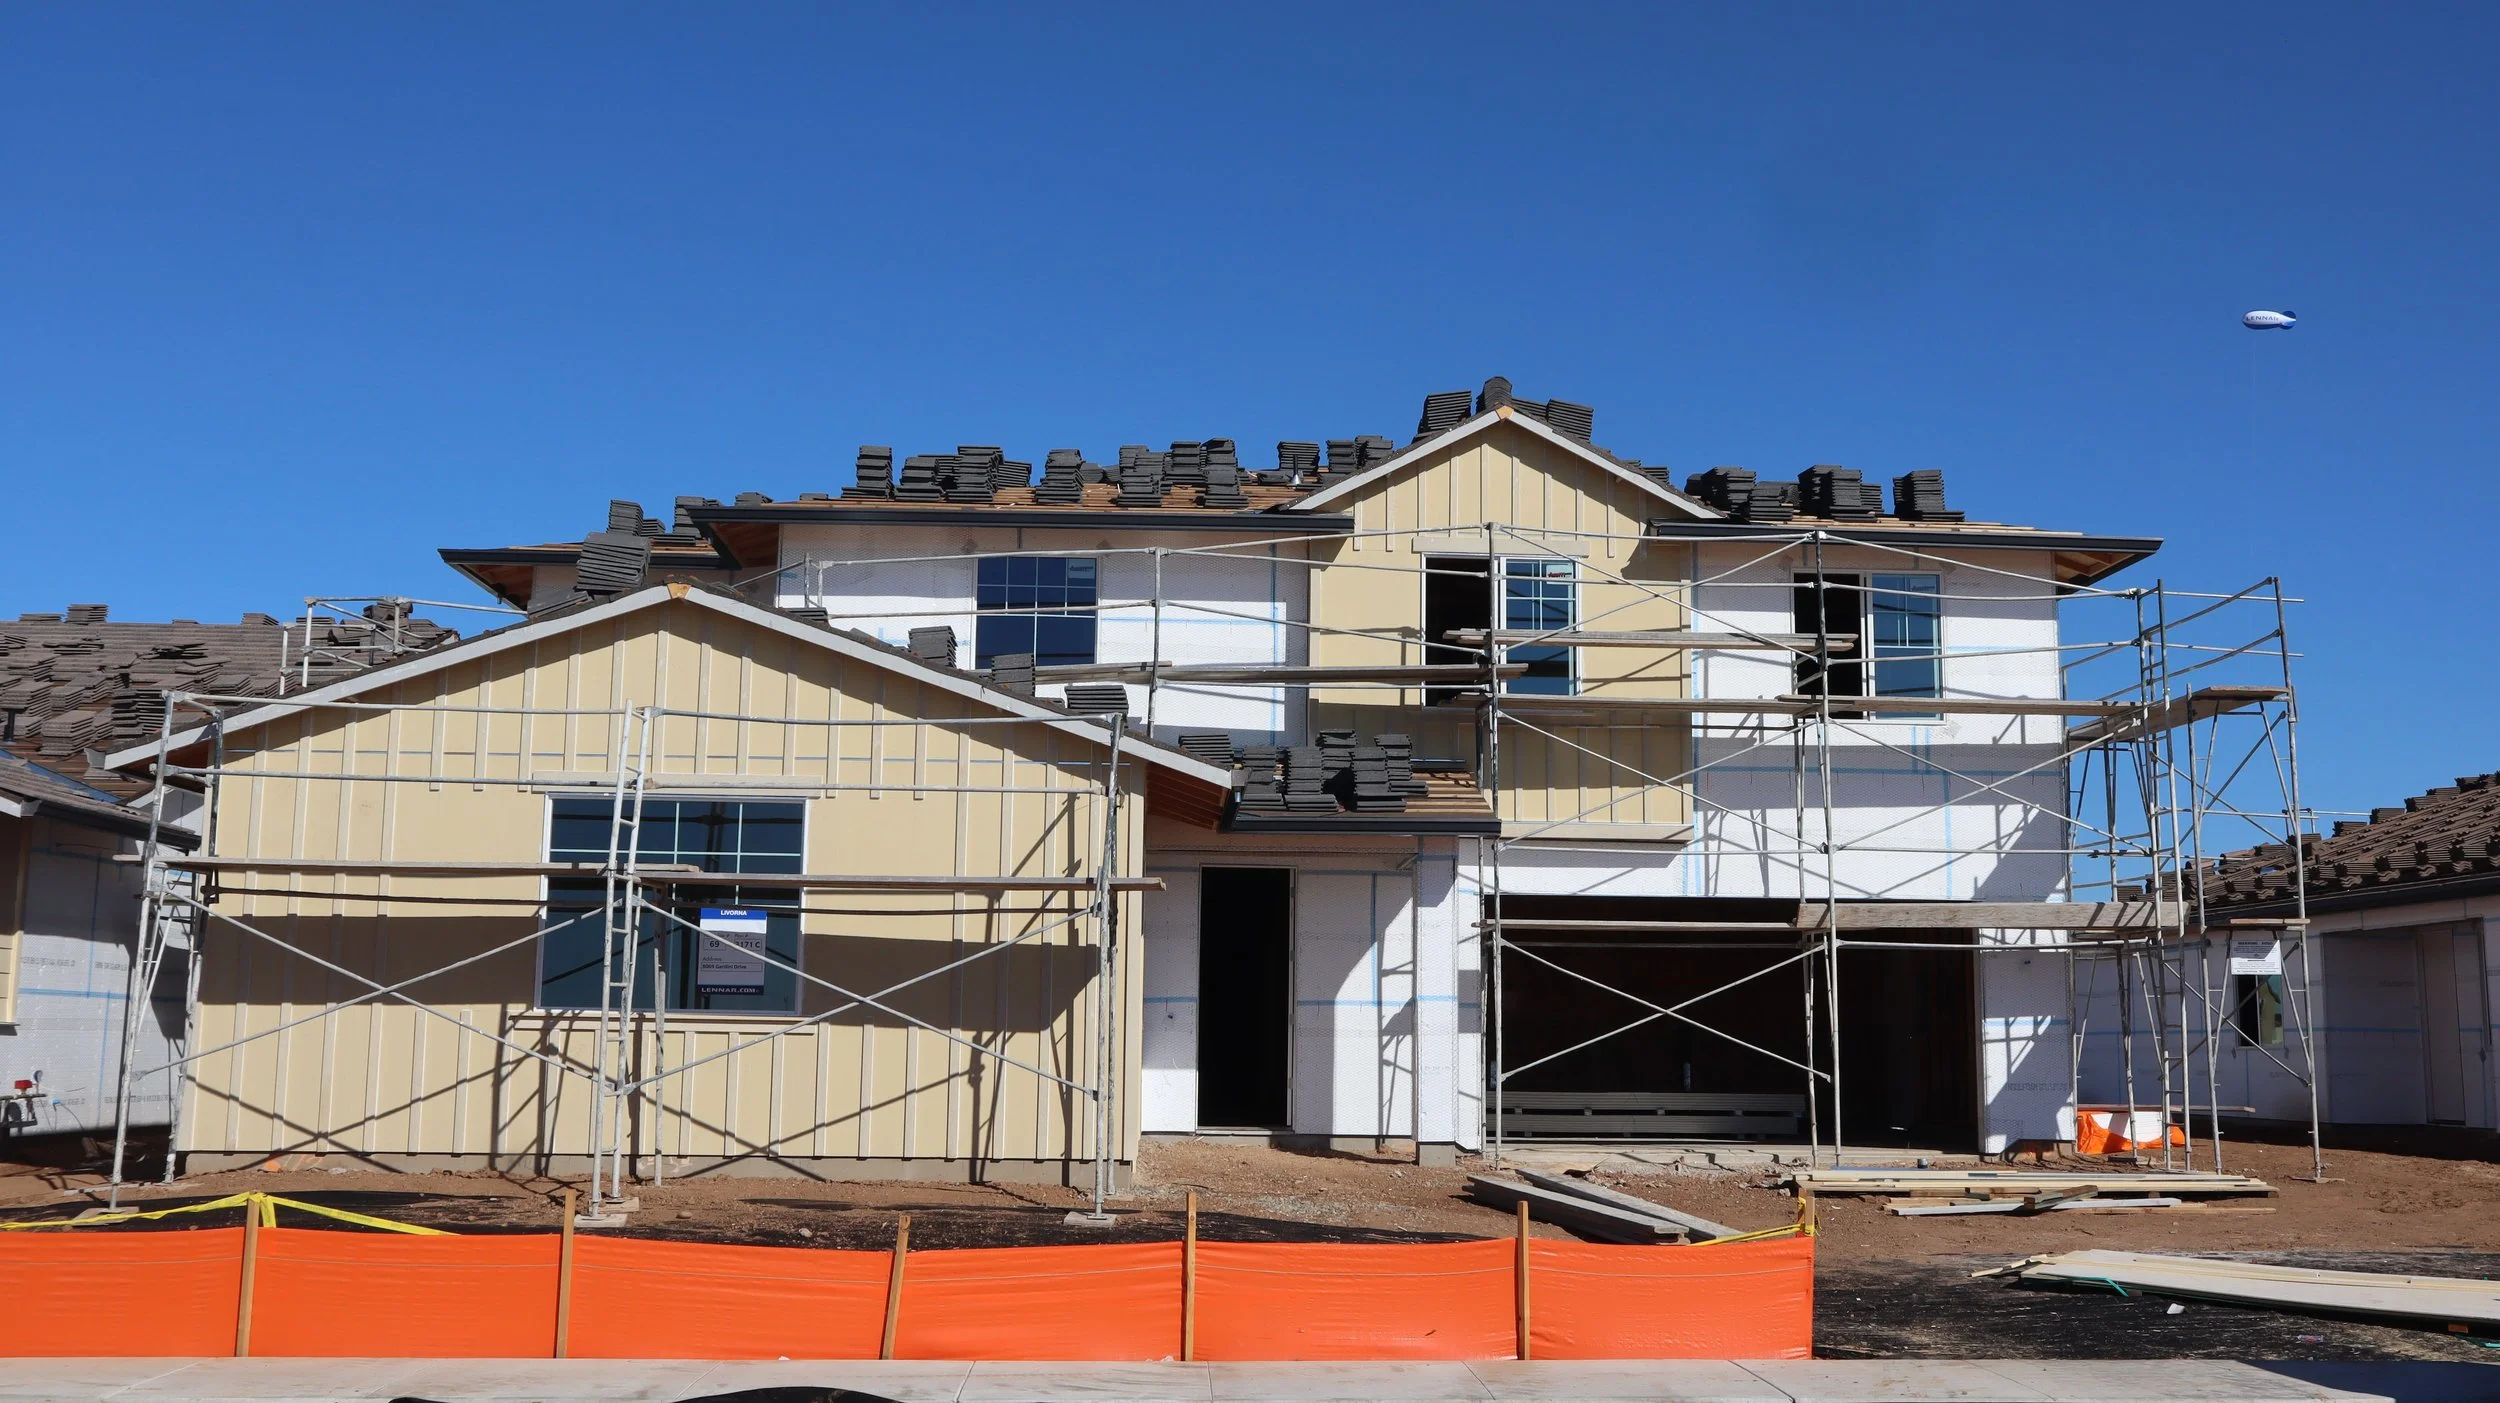
New Construction vs. Resale: Which West Michigan Home Fits Your Budget and Timeline?
New construction offers modern systems, possible builder incentives and fewer immediate projects. Resale may offer established locations, mature landscaping and more negotiating history. Use this West Michigan comparison to evaluate the complete cost, timeline and tradeoffs—not just the sticker price.
Should You List Your West Michigan Home During the Holidays—or Wait Until January?
Holiday listing or January launch? The better choice depends on your home’s readiness, your schedule and today’s competition—not a rule about the calendar. Here is a practical, data-informed way for West Michigan sellers to decide.
¿Qué pasa si el comprador no consigue su préstamo hipotecario para comprar su casa?
Una carta de preaprobación ayuda, pero no garantiza que el préstamo llegará al cierre. Esta guía explica qué puede suceder cuando el financiamiento falla, cómo influyen la contingencia, la tasación y los plazos, y qué puede hacer un vendedor de West Michigan para reducir el riesgo.
Your Home Has Showings but No Offers—What Should You Change?
Showings are evidence that buyers are interested enough to visit. No offers usually mean something is breaking down after they arrive. Here is how West Michigan sellers can identify the real objection and make a focused, evidence-based adjustment.
¿Conviene comprar casa en West Michigan ahora o esperar hasta 2027?
Esperar una tasa más baja puede parecer prudente, pero nadie conoce con certeza el mercado de 2027. Esta guía ayuda a compradores de West Michigan a decidir según su pago, ahorros, estabilidad, opciones actuales y tiempo de permanencia.
How to Sell a House in Grand Rapids, Michigan: A Step-by-Step Guide
Selling your home in Grand Rapids takes more than choosing a price and putting up a sign. This step-by-step guide covers the local market, preparing your property, marketing, offers, disclosures, closing expenses, and planning what comes next.
Will My Property Taxes Increase After Buying a Home in Michigan?
The seller’s current property tax bill may not reflect what a Michigan buyer will pay after closing. This guide explains taxable value, uncapping, millage rates, the Principal Residence Exemption and how a tax increase can affect mortgage escrow and the monthly payment.
How Much Equity Do You Have in Your West Michigan Home—and What Can You Do With It?
Home equity is more than an online estimate minus your mortgage balance. Learn how current comparable sales, mortgage payoff information and estimated selling expenses can help you plan your next move—without committing to sell.
What Does It Really Cost to Buy a Home in Michigan?
The down payment is only one part of a homebuyer’s cash plan. Learn how earnest money, inspections, closing costs, prepaid expenses, moving costs and reserves fit into your West Michigan home purchase.
Should I Buy a Home Now or Wait? A Guide for West Michigan Buyers
Wondering whether to buy a home now or wait? These five questions help West Michigan buyers weigh their budget, savings, financing, local options, and timeline.
¿Pueden sus pagos de renta ayudarle a calificar para una hipoteca?
Pagar la renta a tiempo puede aportar información útil en ciertos procesos hipotecarios, pero no siempre aparece automáticamente en su crédito. Esta guía explica las rutas actuales, qué documentos conservar y cómo preparar un plan de compra en West Michigan.
What Happens to Your Mortgage When You Sell a Home in Michigan?
You can sell a home before the mortgage is paid off. Here is how the payoff, other liens, closing costs, escrow refund and remaining proceeds are handled.

¿Debe Aceptar una Oferta Contingente a la Venta de Otra Casa?
Una oferta contingente puede ser viable si la vivienda del comprador está bien posicionada y el contrato protege sus fechas. Use estas preguntas antes de aceptarla.

7 Questions to Ask Before Signing a Michigan Buyer Agreement
A buyer agreement should make your representation, services, compensation and exit terms clear before the right West Michigan home appears. Use these seven questions before you sign.

What Happens If the Appraisal Comes In Low When Selling a West Michigan Home?
Your buyer agreed to the price, but the appraisal came in lower. Learn what that means, what the contract may allow and how West Michigan sellers can respond without making a rushed decision.

Builder Incentive or Lower Price: Which New-Construction Deal Is Better in West Michigan?
A builder may offer closing costs, a mortgage rate buydown, upgrades or a lower price. Here is how West Michigan buyers can compare the real value of each option before signing a new construction contract.

Kent & Ottawa Market Report | October 12, 2026
West Michigan’s October 2026 housing update for Kent and Ottawa counties: current median prices, inventory, sales pace, mortgage-rate context, and practical guidance for buyers, sellers, and homeowners planning their next move.

What Stays With the House When You Sell a Home in Michigan?
Selling a home in Michigan? Learn what fixtures, appliances, TV mounts, smart-home devices, window treatments and other items commonly stay—and why the purchase agreement controls.
Kent County Housing Market Update.
Kent County Housing Market Update: What Buyers and Sellers Need to Know | August 3, 2026
Weekly Market Brief · Kent County, MI
Kent County Housing Market Report: August 2026
Published August 3, 2026 · Sam Avila, Avila Home Group
Kent County remains competitive: prices are holding firm, well-positioned homes are moving quickly, and mortgage rates have climbed for four straight weeks. Here’s what matters—and how to use it when planning your next move.
The Numbers
$335,000
▲ 3.1% YoY
Kent County median sale price
|
13 days
Median days on market
|
99.0%
Sale-to-list price ratio
|
1.2 mo
Months of supply — still well below a balanced market
|
6.66%
▲ 0.08 pt WoW
30-year fixed mortgage rate, national avg.
|
+13%
Regional home sales volume, 2025 vs. 2024 (still 15% below 2019–2020 levels)
|
For Buyers
- Good listings can still move quickly. With roughly 1.2 months of supply, buyers should be fully underwritten and clear on their priorities before the right home appears—especially in popular price ranges.
- Rates deserve a strategy, not a panic button. Freddie Mac’s national weekly average reached 6.66% on July 30. On a $300,000, 30-year loan, the principal-and-interest payment is roughly $92 more per month than at 6.20%.
- Price still matters. A 99% sale-to-list ratio suggests most successful offers are landing near asking price, but property condition, competition, concessions, and neighborhood activity can change the playbook.
For Sellers
- Price growth is positive, not automatic. The latest local snapshot puts Kent County’s median sale price near $335,000, up about 3.1% year over year. That supports sellers, but it does not rescue an aggressive list price.
- Preparation creates leverage. A 13-day median means buyers make decisions quickly. Strong presentation, accurate pricing, and a clear launch plan help a home earn attention before the listing becomes yesterday’s news.
- The market rewards precision. Regional sales volume improved in 2025 but remained below 2019–2020 levels. Today’s seller advantage is real, yet execution still separates the standouts from the sitters.
If you’re considering a move this fall—or simply trying to understand your current equity—I’m happy to prepare a neighborhood-specific review. No generic estimate, no pressure, and no crystal ball wearing a name badge.
Have a question about what these numbers mean for your street, your equity, or your next move? Call or text 616-797-0001, request a personalized home-value review, or schedule a conversation.